Operational Resilience: The Dangers of Reactive Risk Management
Operational resilience has become an increasingly important priority for financial services firms. For those within the scope of the FCA and PRA operational resilience regimes, specific requirements are designed to ensure that important business services can continue through severe but plausible disruption. Yet organisations can still fall into a reactive approach, addressing weaknesses only after disruption occurs. The problem with reactive risk management is that, by its nature, it comes too late. By the time a disruption occurs, the damage may already have been done. Customers may have been unable to access services, transactions may have failed, and the firm’s reputation may have suffered. The costs can be significant, both financially and in terms of customer trust. For firms subject to the FCA’s operational resilience rules, a reactive approach can also make it more difficult to meet regulatory requirements. Firms must identify their important business services, set impact tolerances, and carry out mapping and scenario testing. Since 31 March 2025, firms within scope have been required to be able to remain within their impact tolerances for each important business service during severe but plausible disruption. The FCA’s March 2026 review of operational resilience self-assessments reinforces this point. The FCA highlighted the importance of regularly reviewing important business services and impact tolerances, carrying out sufficiently challenging scenario testing, and using the results to identify vulnerabilities and drive remediation. Operational resilience should therefore be treated as an ongoing process rather than an exercise undertaken only when disruption occurs. The human element is another important consideration. When firms are constantly firefighting, it can create a culture of stress and burnout. Employees may feel that they are always playing catch-up rather than proactively managing the risks they face. Over time, this can contribute to lower morale, higher turnover and, ultimately, a less resilient organisation. Operational resilience therefore requires more than preparation. Firms need to understand the resources and dependencies supporting their important business services, test severe but plausible scenarios, identify vulnerabilities, and take action to address them. Lessons from testing and real-world incidents should then feed back into future assessments, helping firms continuously strengthen their resilience. How Complyport Can Help Moving from reactive risk management to a more proactive approach requires clear processes, accountability and visibility across the organisation. ComplyPortal, Complyport’s cloud-based Compliance Management System, can help firms manage operational resilience activities in a more structured and consistent way. Customisable workflows can support the review of important business services, impact tolerances, scenario testing and identified vulnerabilities. Tasks, owners and deadlines can be assigned to remediation actions, with follow-up activity tracked through to completion. Policies, testing records, assessments and supporting evidence can also be maintained within the platform’s document management system, creating a clearer audit trail of resilience activity. This makes it easier for compliance teams and senior management to monitor progress, maintain oversight and evidence the decisions and actions taken. By bringing workflows, responsibilities, documentation and evidence together in one place, ComplyPortal can help firms take a more organised and proactive approach to operational resilience. Ready to strengthen your approach to operational resilience? Discover how ComplyPortal can help you manage compliance activities, responsibilities and evidence more effectively.
Complyport Welcomes HSBA Students to its Limassol Offices
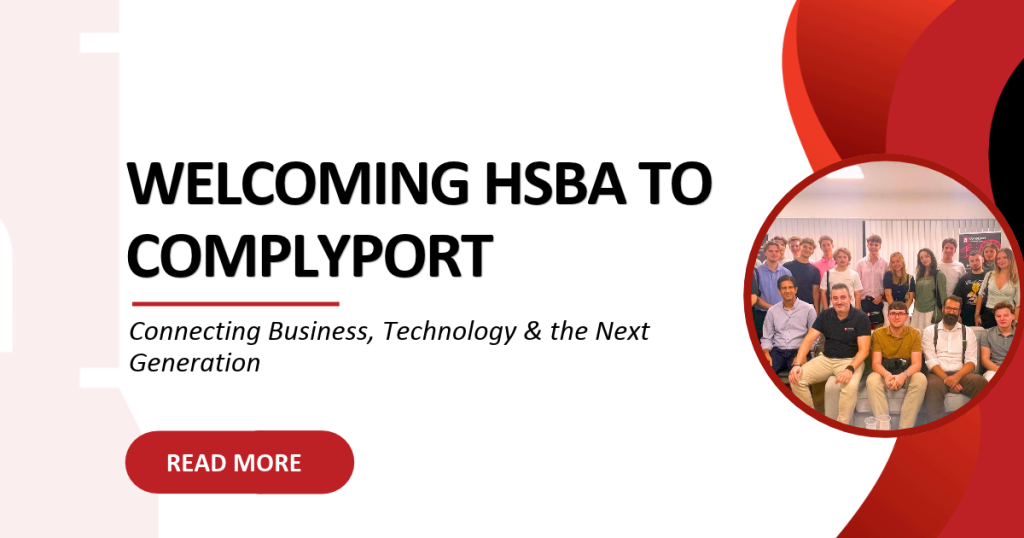
Complyport was pleased to welcome a group of students from Hamburg School of Business Administration (HSBA) to our offices in Limassol as part of their study trip to Cyprus. During the visit, Panayiotis Omirou, Managing Dirctor at Complyport Technologies, introduced the students to Complyport’s business model and growth journey, sharing how the company has evolved over the years and how technology has become an integral part of our offering to the financial services industry. The discussion also explored Complyport’s technology solutions and the role technology plays in helping financial services firms navigate increasingly complex regulatory and compliance requirements. A key part of the presentation focused on MAP FinTech, Complyport’s award-winning RegTech platform for Regulatory Reporting and Trade Surveillance. We shared the story behind the platform, how it has evolved in response to changing regulatory requirements, and how technology and automation can support firms across multiple jurisdictions. The visit provided a valuable opportunity for an open exchange with the students, who were able to ask questions and gain practical insights into our business, growth, and technology journey. We were delighted to host the HSBA students in Limassol and share our experience and insights with the next generation of business and technology professionals. Image #1 Image #2 Image #3 Image #4
Meet us at the iFX EXPO International 2021
Let’s meet at the iFX EXPO! We are pleased to announce our participation as exhibitors at the iFX EXPO International 2021, in Limassol. We shall be delighted to meet you at one of the largest financial B2B expos in the world, which will be held at Parklane Hotel in Limassol, on 5-6 October 2021. iFX EXPO is an annual highlight for the financial services sector since 2012, connecting top-level executives in online trading, financial services and fintech from around the world. Meet MAP S.Platis and MAP FinTech teams at booth No.10. Visit us to talk about how we can assist towards the setting-up and licensing of your financial services firm as well as exchange views on the latest trends in the field of financial services regulatory and business consulting for brokerage and investment advisory firms, asset managers, investment funds and fund managers, payment and electronic money institutions and banks. Also, get a chance to meet our regulatory technology experts, MAP FinTech, a leading and award-winning UK and EU regulatory technology provider for the financial services industry, specialising in reporting and monitoring solutions as EMIR, MiFID II/MiFIR, ASIC, SFTR, FATCA, CRS DAC6, Best Execution Monitoring, RTS 27/28 reporting, KYC & AML Transaction Monitoring, Trade Surveillance (Market Abuse), and eKYC (Screening, eIDV, Document Authentication), all being delivered under the single and powerful Polaris platform. We look forward to meeting you in Limassol!
Understanding Margin Lending and Prime Brokerage under SFTR
SFTR & SFTs Defining SFTR & SFTs The Securities Financing Transactions Regulation (SFTR) applies to transactions linked to the build-up of leverage, pro-cyclicality, liquidity and maturity transformation, and interconnectedness in the financial markets. It aims to regulate securities financing activities by setting out reporting requirements data access, collection, verification, aggregation, comparison and publication of data for securities financing transactions (SFTs) by trade repositories (TRs). An SFT could be any transaction in which securities are used to borrow cash or vice versa. For the most part, this includes repurchase agreements (repos), securities lending activities, and sell/buy-back transactions. In each of these transactions, ownership of the securities temporarily changes hands in return for cash. Following the SFT’s conclusion, this change in ownership reverts itself with both counterparties ending up with what they had initially possessed, plus or minus a small fee depending on the transaction’s purpose. Ultimately, SFTs act like collateralised loans. The categories of SFTs in SFTR include: Repurchase transactions Securities or commodities lending and borrowing Buy-sell back or sell-buy back transactions Margin lending transactions When Does a Transaction Fall Under the Scope of SFTR? There are two main scenarios under which a transaction may be affected by SFTR: The transaction leads to the build-up of leverage, procyclicality and interconnectedness in the financial markets or it contributes to liquidity and maturity transformation. The transaction is subject to margin agreements between financial institutions and their clients. The transaction should be a secured (i.e. collateralised) transaction that involves the temporary exchange of cash against securities or securities against other securities. If the collateral giver defaults, the collateral taker retains the collateral to cover potential losses. Margin Lending As per SFTR, the definition of a margin lending transaction is “a transaction in which a counterparty extends credit in connection with the purchase, sale, carrying or trading of securities, but not including other loans that are secured by collateral in the form of securities”. With regards to reporting margin lending transactions, the purpose of SFTR is to capture transactions that serve the same purpose as repurchase transactions, buy-sell back transactions or securities lending transactions. These transactions pose similar risks to financial stability by allowing the build-up of leverage, pro-cyclicality and interconnectedness in the financial markets or by contributing to liquidity and maturity transformation. While margin lending includes transactions subject to margin agreements between financial institutions and their clients, ones in which financial institutions provide prime brokerage services to their clients, loans that do not pose systemic risks are not included. These might be, for example, loans for corporate restructuring purposes. Prime Broker ESMA defines a prime broker as “a credit institution, a regulated investment firm or another entity subject to prudential regulation and ongoing supervision, offering services to professional investors primarily to finance or execute transactions in financial instruments as counterparty and which may also provide other services such as clearing and settlement of trades, custodial services, securities lending, customised technology and operational support facilities”. When is a Prime Brokerage Captured by SFTR? ESMA’s position is that the margin lending reporting obligation should only apply to prime brokerage margin lending, i.e. cash lending from prime brokers to their clients against collateral as part of a prime brokerage agreement. ESMA further explains the context of prime brokerage margin lending: Prime brokerage margin lending takes place on a portfolio basis, against a pool of collateral, by using or reusing assets in the client’s margin account as collateral. The relationship between financial entities involved in margin loans is relatively simple compared to other types of SFTs. The basic prime brokerage margin lending scenario involves the borrower and the lender as the two counterparties. Lenders are prime brokers, while borrowers are usually investment funds. In the context of prime brokerage, margin lending does not rely on standardised master agreements that govern most other types of SFTs. It typically relies on bilateral prime brokerage agreements between the lender and the borrower that specify the terms and conditions of the margin account. Prime brokerage agreements are negotiated between prime brokers and their clients. What About CFD Brokers? CFD trading cannot be captured by margin lending since the offering of leverage, which can be considered as an extension of credit, is not in connection with the purchase, sale, carrying or trading of securities. Also, there is no temporary exchange of cash against securities or securities against other securities. However, if a CFD broker also provides the service of actual securities trading, it needs to determine whether it is considered a prime broker in relation to the margin lending transactions provided to its clients. By doing this, the CFD broker will be able to assess whether or not this credit extension is captured by SFTR. How Does Margin Lending Work For example, brokerage customers signing a margin agreement can borrow up to 50% of the purchase price of marginable investments. In other words, investors can use margin to potentially purchase double the amount of marginable stocks than they could when using cash. Keep in mind, however, that the exact amount varies depending on investment. If you have, say, $5,000 in cash in a margin-approved brokerage account, you could buy up to $10,000 worth of marginable stock. In other words, you would pay 50% of the purchase price and your brokerage firm would loan you the other 50%. That way you have $10,000 in buying power. Similarly, you can often borrow against the marginable stocks, bonds and mutual funds already in your account. For example, if you have $5,000 worth of marginable stocks in your account and you haven’t yet borrowed against them, you can purchase another $5,000. The stock you already own provides the collateral for the first $2,500, while the newly purchased marginable stock provides the collateral for the second $2,500. You now have $10,000 worth of stock in your account at a 50% loan value, with no additional cash outlay. Because margin uses the value of your marginable securities as collateral, the amount you can borrow fluctuates on a daily basis along with the value